First published 6 Nov 2026, 10:32am
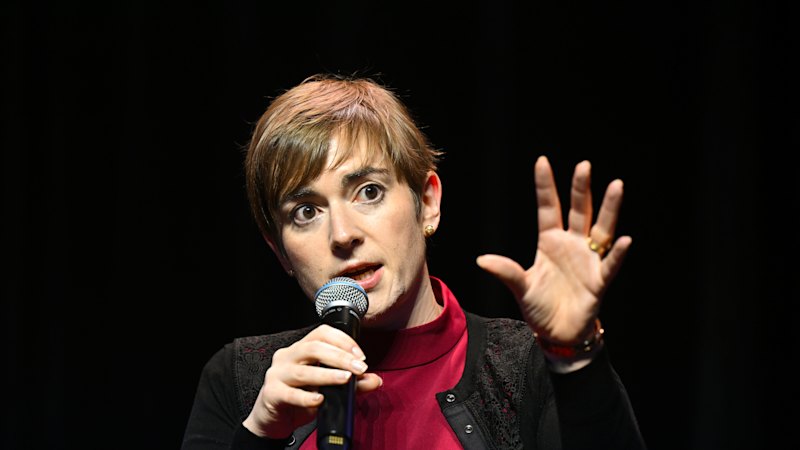
RBA Governor Michele Bullock announced a November rate hike. Picture: Nikki Short
The RBA board must feel as though it’s being gaslighted.
Whenever it hikes the cash rate, Australians are up in arms, pleading that we can’t possibly afford to pay any more on our mortgages than we already do. We also can’t afford rents, or filling cars with petrol, or buying enough groceries, or paying our medical bills.
Sometimes, these pleas are enough to cause a ripple of concern to run through the central bank’s boardroom. A board member’s steely glare of fiscal determination may soften slightly into an almost sympathetic furrowed brow.
On occasion, there may even be a split decision on whether the rate should really be raised.
And then, no sooner do we finish making our case, than we go out and throw our money at the next big spending event.
MORE: The $3k secret RBA doesn’t want Aussies to know
On Melbourne Cup Day, for example, Finder research estimated we would gamble $351 million as a nation.
That’s right. On the very day the central bank was preparing to hand down a fifth rate hike for the year, we were throwing eye-watering sums of money into the abyss.
Large crowds gather to spend on gambling, food and beverages at our big race days.
And waking up a bit dusty on Wednesday, as analysts and commentators argued about excessive government spending or out of date methods for stifling inflation, we began discussing the Black Friday sales, which officially begin in Australia on 27 November, but which are being advertised daily via brand newsletters and socials already.
Last year, we spent $23.8 billion across four days of sales from Black Friday to Cyber Monday.
MORE: Woman quits Aus for $90k home, regrets it
Of course, after Cyber Monday comes Travel Tuesday, where we scramble to purchase great deals on plane tickets, hotels, cruise ships and guided tours.
Those deals enable us to head off on holidays and spend like people on holidays spend.
After that, there’s the Christmas shopping rush, followed by the Boxing Day sales.
By the time the RBA meets in February, it will be armed with a couple of months’ worth of spending data that will suggest that we can indeed absorb yet another rate hike.
And it may even be a little angry with us for gaslighting it so badly.
It will hike the rate again and we will be outraged, before we begin planning our big spend on Valentine’s Day, followed by Mother’s Day and then gearing up for the end of financial year sales.
Crowds flocked to the mall for the 2025 Black Friday sales. Picture: Andrew Henshaw
We just keep going round and round in a constant cycle of big spending events that we simply can’t bring ourselves to forego.
The RBA wants to make sure that inflation expectations don’t become embedded above where they want it to be.
But we also need to change our spending expectations. It may seem impossible to spend less, but it’s really not.
This week I ate a roast beef and pickle sandwich that I made at home for a total cost of about $2.50. I could buy that same sandwich, where I work in Surry Hills, and it would cost about $15 extra. If I ordered it delivered to my office from a cafe via Uber Eats, you could add another $10 at least to that.
MORE: Man cops $225k fine over shock backyard act
As I write, there are Uber Eats bikes flying by all over the city. Some people are paying at least $20 extra for a very similar lunch to the one I made at home.
These are just examples of what our nation is doing as a whole.
There are many borrowers out there barely getting by and I don’t think for a second that they are spending frivolously at all. People are skipping meals, going without medicine, figuring out what bills they can pay late and making countless other sacrifices just to hang onto their home.
The RBA will meet five days before Valentine’s Day in 2027. Picture: Instagram
It’s the group-spend of the Australian consumer hive-mind that is the problem. And the mortgage holders are the ones punished for it via rate hikes.
The hive-mind must be deterred from spending in order to pull inflation back. And slugging mortgage holders won’t do that. It’s another reason why we need a different approach.
We could raise the GST, or raise compulsory super contributions. We could cut government spending, increase taxes on luxury items, or subsidise the increase of supply to meet demand.
Help us improve your reading experience
Got a minute? Your feedback will help us build a better experience for you.