A rout of AI related stocks dragged Wall Street down on Friday, while another rise in oil prices and the massive theft from the world's biggest crypto exchange, Binance, didn't help sentiment.
The ASX is on edge this morning, priced for a flat opening ahead of the RBA rates decision and results from the big banks this week.
Follow the day's financial news and insights from our specialist business reporters on our live blog.
Disclaimer: this blog is not intended as investment advice.
Prices current at around 7:00am AEDT
Choose what information you see below by using filters
Mon: Home prices (Oct), Dwelling approvals (Sep) Westpac FY
Wed: Household spending indicator (Sep), Amcor FY, Light & Wonder Q3
Thu: Trade balance (Sep), RBA speech Deputy Governor Hauser, NAB FY, James Hardie H1
Fri: US — Non-farm payrolls, unemployment (Oct)
The RBA rates decision on Tuesday is the big event for the week.
There's not much point previewing it, the subject has been thrashed to death from pillar to post; that is everyone from the economists at the four big pillar banks down to the humblest blog post … and there's been furious agreement that inflation is too high and the RBA board will raise the cash rate by 25bps to 4.85%. ( They said that about the RBNZ last week too, but that's a different story we suppose).
The more important issue may well be the post-decision communication from the Board and the Governor's post decision media conference.
The other releases of note locally include the always volatile dwelling approvals (later this morning), the ABS Household Spending Indicator (Wednesday), which while being flat month-on-month has a strong annual growth of 6.8% and international trade (Thursday) which may swing into deficit due to a sharp increase in the price of refined fuel imports in September.
This week also marks to start of the big banks' mini reporting season — that is, for banks not named the "Commonwealth Bank of Australia", which marches to a different beat and released its $11 billion full year profit in August.
Westpac kicks things off this morning , followed by NAB on Thursday and Macquarie posts its half year numbers on Friday.
ANZ will give the blog something to mull over next Monday, November 9.
Offshore, the big events are very much US-centric… mid-term elections (Wednesday) and the key jobs numbers of non-farm payrolls and unemployment on Friday.
The Bank of England meets on Thursday and is tipped to raise rates by 25bps to 4.0%.
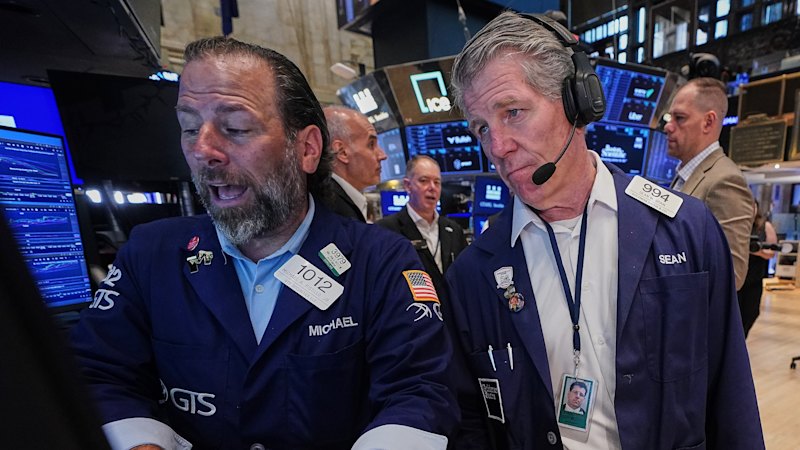
Wall Street closed the week, maybe not in a blind panic, but there was certainly a disquieting dumping of stocks as investors fled to the exits and the weekend.
All three key indices fell sharply, the tech-centric Nasdaq fell the hardest and is down almost 8% from its record high of just three weeks ago.
The dump saw the global MSCI down 1.5% for the day, while the pan-continental Eurostoxx 600 fell a comparatively modest 0.4%.
The tech-lite ASX is unlikely to be as affected by anxieties over cash-burning AI investments as Wall Street was on Friday.
When trading closed on Saturday morning (AEDT) ASX 200 futures were flat, or to be precise 4 points (0.04%) lower.
The tech rout was sparked by disappointing quarterly results from Intel and Amazon released late on Thursday.
While Amazon pared losses as the session progressed, Intel shares cratered, down almost 30%.
Chip stocks veered sharply lower, with Nvidia down more than 4%.
The broader chips index shed 7.2%, slumping to a monthly loss of more than 15%. Server makers Dell and HP dropped 10.8% and 9.6%, respectively.
"It's fair to say that this week, not just today, has been very much about the future of AI and what that's going to look like, whether there will be a positive return on investment and if so, how quickly," Wealthspire Adivors Oliver Pursche told Reuters.
"Companies that are performing and meeting the very lofty expectations that have been set are doing well," Mr Pursche said.
"Those that are falling short and seem to be missing the mark or not executing as expected are getting punished."
On the subject of being punished, cryptocurrency related firms all got walloped on the news that hackers nicked a lazy $US6.3 billion ($9 billion) worth of various stable coins, such as Bitcoin and Ethereum, while no-one was looking at the world's biggest crypto exchange Binance.
Listed crypto firms Coinbase, Strategy and Robin Hood all fell between 7 and 11%. All said they were safe, but they would say that.
Putting aside the Binance contretemps, it's worth noting that hackers have made off with about $US3 billion in crypto in around 150 incidents.
US Treasuries were one of the beneficiaries of the tech rout as investors decided they were a safer bet at the moment, which is saying something.
The benchmark 10-year yield closed the month with its biggest monthly drop in nearly three years.
Gold, once also considered a safe haven, didn't benefit from the conniptions — indeed, it slumped (-3.5%) to a one-year low, along with other precious metals. Silver shed 6.5% and palladium shed 3.0%.
"The sky is falling," independent metals trader Tai Wong told Reuters with a dramatic flourish.
"Metals will not be able to escape the gravity well of a nasty stock correction. Earnings have been the foundation of the AI rally and now that pillar is showing some cracks."
Oil seems to be blithely ignoring Mr Wong's "gravity well". The key benchmarks both gained more than 2% on Friday.
For the month, Brent finished almost 14% higher , while WTI rose even more, up 15%.
On Friday, a tanker in the Strait of Hormuz was hit by explosive devices, believed to be limpet mines attached by a small boat, according to UKMTO, the British maritime security service.
It is believed to be the first successful use of limpet mines since the war began in February. Probably not the last either.
Good morning and welcome to another day on the ABC markets and finance blog.
Stephen Letts from ABC business team limbering up for a blow-by-blow coverage of the day's events, where every post is hopefully a winner, but none should be construed as financial advice.
Wall Street closed sharply lower on Friday , driven down a major sell-off of AI-related stocks.
The ASX, largely an AI-free zone, is poised to open flat, with futures trading pointing to only a marginal loss ahead of tomorrow's RBA rates decision.
We've already seen October's home price numbers — a nationwide decline of 1.2%.
We'll have more housing news a bit later with September's dwelling approvals being released and Westpac's full year results will be posted very soon — and they are likely to be a key driver of sentiment today.
The key number to look out for is a cash profit of $6.96 billion. That's the consensus forecast among the analysts.
The game's afoot, so let's get blogging.