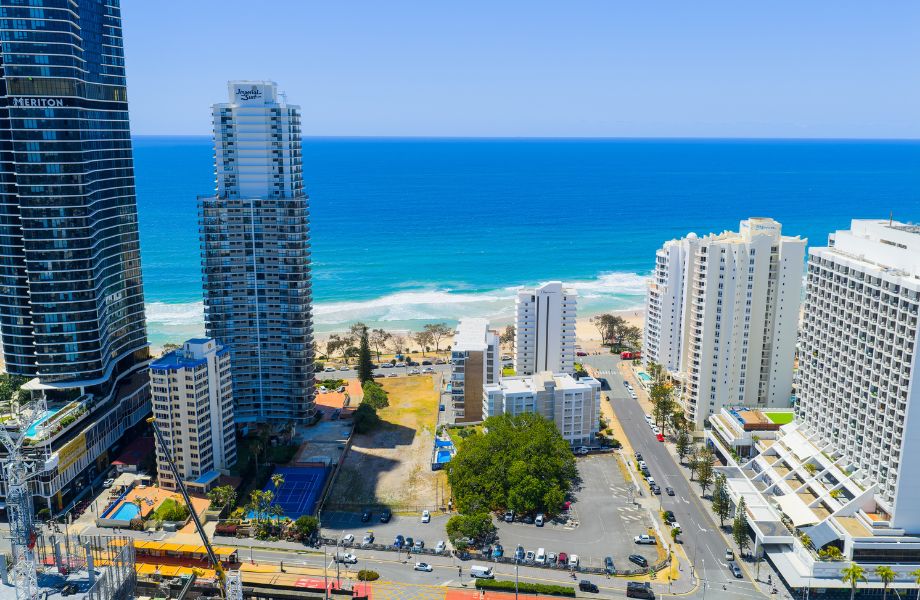

One of Surfers Paradise’s last major beachfront landholdings has finally found a buyer, with a Dubai-based developer paying close to $70 million for the long-dormant site.
The L-shaped beachfront site at 3241 Surfers Paradise Boulevard has been held by Brunei-linked interests for 30 years, laying dormant despite the highrise boom taking place around it.
With frontages totalling about 187.5m across Surfers Paradise Boulevard, View Avenue and The Esplanade, the vacant block last changed hands in 1996 for $15 million.
Colliers Gold Coast director Steven King and sales executive Jackson Robinson handled the sale.
“It was predominantly residential developer focused interest, with a little inquiry from hotel groups. Ultimately, the purchaser was an international developer from the Middle East,” King said.
He would not confirm the identity of the buyer or the final sale price.
The deal reportedly closed last week for close to $70 million.
“It’s the largest single lot sale price achieved in Surfers Paradise and it’s the second largest single lot sale price on the Gold Coast,” King said.
The sale is the most significant Glitter Strip deal since 2024 when Monaco Property Group paid $70 million for the former Nobby’s Outlook site at 122-130 Marine Parade, Miami.
That block is currently being redeveloped as Nalu, a $500 million luxury beachfront project of 44 apartments and where the Queensland apartment record this month was reset with the $32 million sale of its “ultra-penthouse”.
King said there had been a “handful” of serious bidders on the Surfers Paradise block including international and domestic developers attracted to the rare waterfront position.
“It’s a significant transaction, which is going to offer a significant supply of apartments in the future.”
Despite resilient buyer demand, Gold Coast apartment development remains constrained by construction costs and feasibility pressures, with the Property Council’s latest Gold Coast Apartment Pipeline Report warning about 60 per cent of projects scheduled for completion in 2028–29 are at risk of delay or withdrawal.
“Most of these developers know where we are in the cycle and when markets tend to bounce back,” he said.
“A project like this would probably take at least three years to get out of the ground so they’re not looking at the short term.
“Yes, they know there are some headwinds right now, but they all know that the growth story of the Gold Coast will quickly change and they need to be prepped and ready for when it does.”
According to King, the deal reflected the confidence of developers who are prepared to commit capital well ahead of delivery.
“This very well-respected international developer obviously identifieed that the Gold Coast has got a very strong future ahead,” he said.
“They wouldn’t make such a big investment if they didn’t believe in the growth story around the Gold Coast.”
Concept plans for the holding include three towers incorporating luxury sky homes, a hotel and serviced apartments, however there was no development application approval in place.
Zoned High Density Residential, the site could support residential, hotel and build-to-rent projects.
It is opposite Surfers Paradise Beach and within walking distance of Cavill Avenue and the light rail network.
Parts of the land have been used as a carpark, while the beachfront section hosted the Imaginator attraction in 2024.